Fears are growing over CoreWeave’s business model and long-term viability, but the ultimate face of the AI bubble may be a tech giant hiding in plain sight.
Oracle Corporation five-year credit default swaps briefly surpassed 300bps today (15 October), according to S&P data, though they edged back to 295bps as US Treasury yields eased. That puts the premium on Oracle CDS far wider than any other constituent in the CDX IG index and about 3x the spread it traded at in early February this year. It is also wider than most names in the CDX HY index basket — a sobering comparison for a company that is often grouped among the big five hypercalers.
“Oracle and CoreWeave both have CDS, making them visible, tradable pressure points for AI credit risk,” said Orlando Gemes, chief investment officer at Fourier Asset Management. “CDS can move fast and lead bonds when volatility hits.”
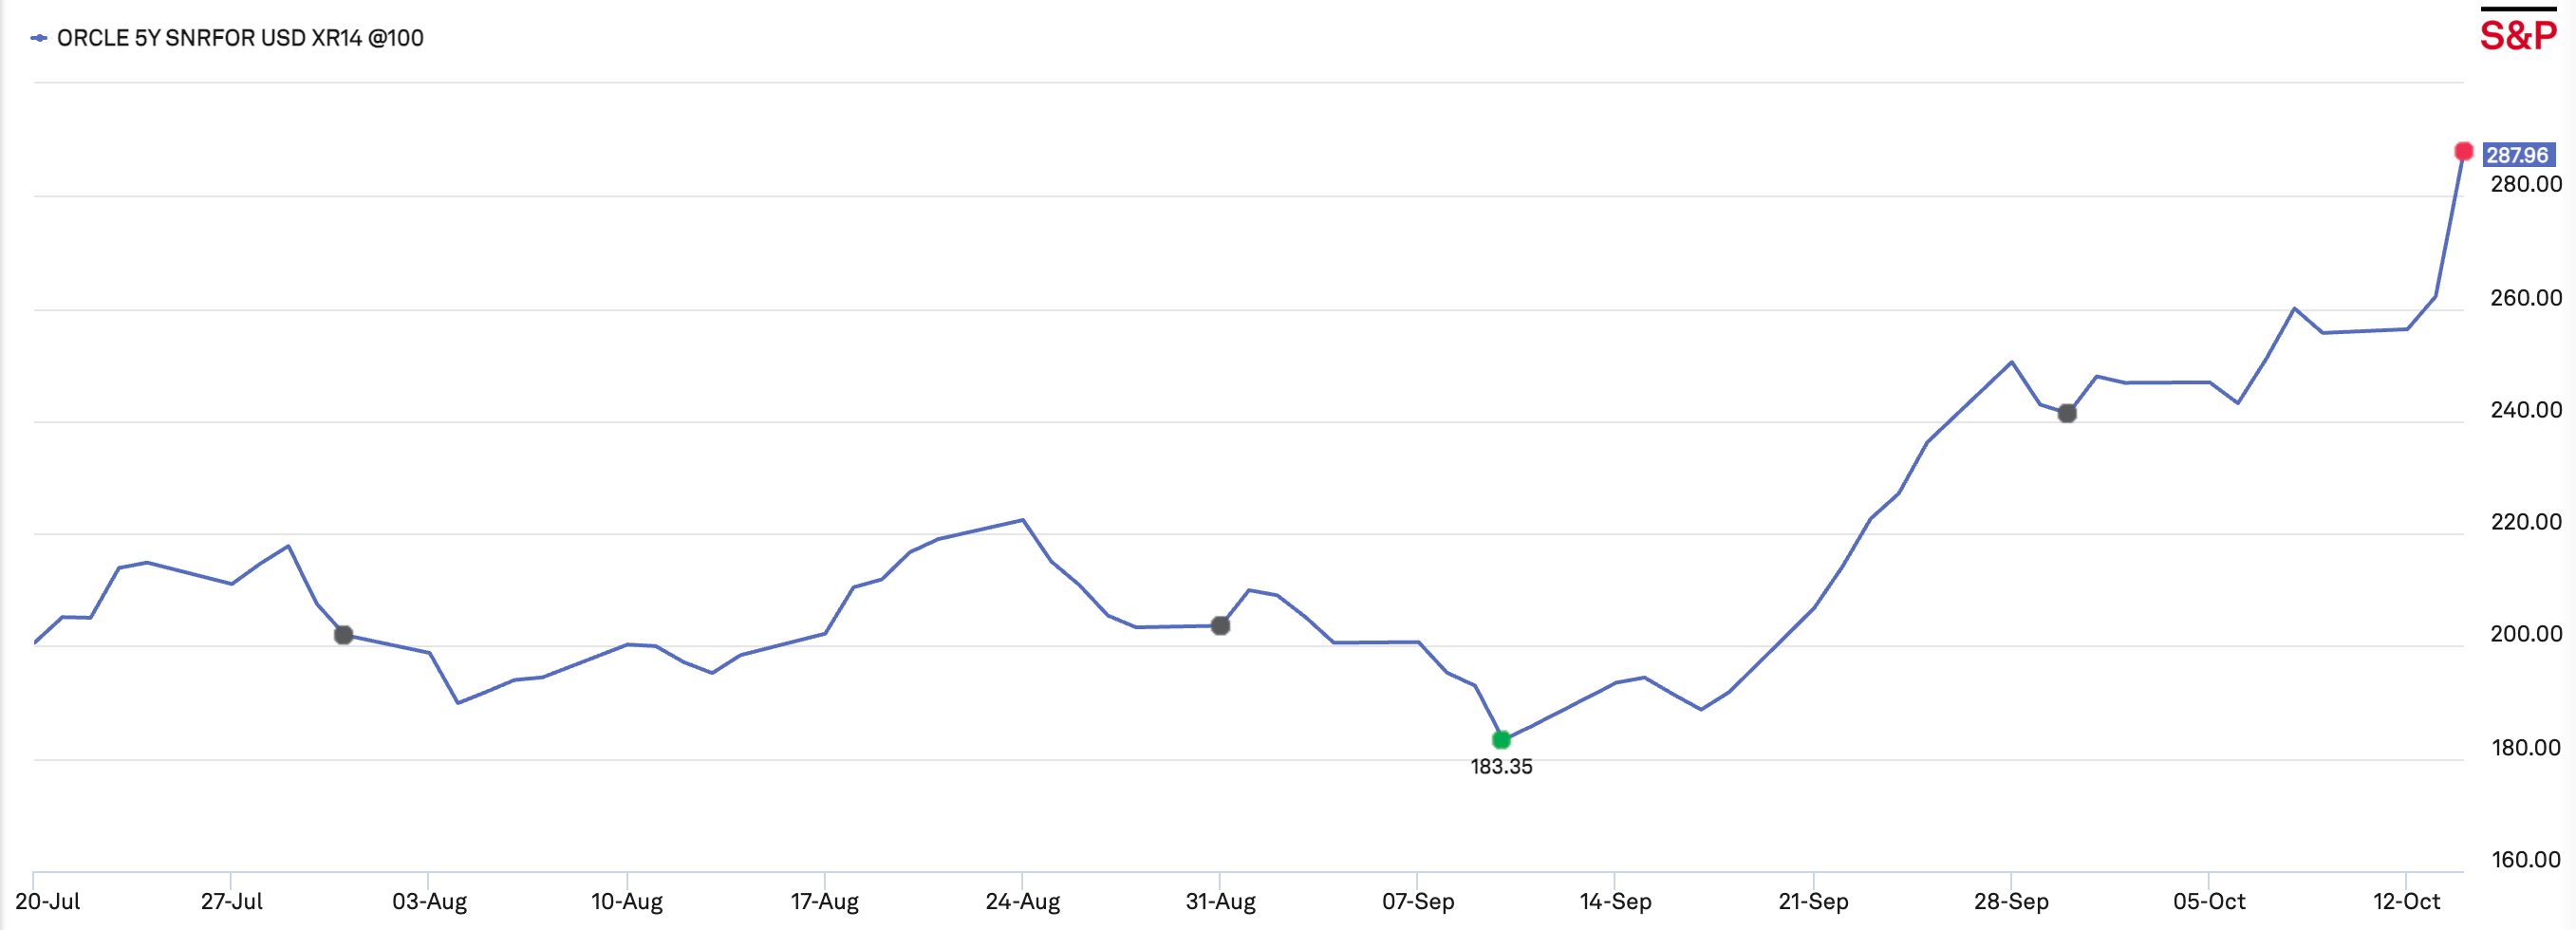
Oracle five-year CDS in bps, at the Thursday (14 October) market close (Source: S&P)
While Oracle’s CDS surge is still a fraction of the 1,160bps premium to cover CoreWeave debt (which briefly surpassed 1,200bps today), the levels reflect investor skepticism that Oracle’s enormous spending on artificial intelligence infrastructure will...