As 9fin stated back in September 2024: “One person’s cooperation turns out to be another’s collusion.” Sure enough, Optimum Communications fka Altice USA sees collusion. Explicitly. “When these creditors decry ‘creditor-on-creditor violence,’ they are really just articulating the traditional logic of a cartel: the belief that collusion between rivals yields better outcomes for those in the cartel,” says the 25 November complaint.
Selecta’s minority bondholders similarly commenced litigation similarly categorizing a cooperation agreement between creditors as an “anticompetitive and collusive agreement between competitors.” However, unlike the Optimum complaint, which goes into great detail identifying a relevant market, antitrust injury theory, and addressing contemplated pro-competitive justification arguments, Selecta’s complaint seems to withhold any detailed preview in favor of waiting for the actual briefing to be filed. Additionally, Selecta’s market is inherently smaller since the cooperation agreement only covers a subset of first lien debt. As the minority bondholders noted in their complaint, “Defendants’ anticompetitive conduct exclusively targeted the market for Selecta Group B.V.’s first lien debt.” In contrast, Optimum’s challenge extends to it’s entire capital structure and the leveraged finance market at large.
While there will be some time before all parties are properly summoned and briefing is scheduled and filed, we still believe that co-op members will argue in the first instance that cooperation agreements in this context are absolutely not per se violations of the Sherman Act. Additionally, we believe co-op members will argue even under the Rule of Reason analysis, these agreements are still not illegal because — as we previously wrote:
- A distressed borrower negotiating with its lenders is not a relevant market that antitrust laws concern themselves with and there is no antitrust injury;
- Even if this was a relevant market, there are reasons to believe that co-ops are pro-competitive;
- Even if this was a relevant market, and co-ops are not pro-competitive, the Noerr-Pennington doctrine is a valid defense.
When we wrote our previous articles, no litigation had been commenced. Although we don’t have any briefing yet, using the complaint filed, we will apply the facts and previews of arguments available to the most relevant case law we are aware of.
If you can’t define the relevant market, you can’t claim the pain (United Airlines)
According to the Department of Justice’s antitrust division, “A relevant antitrust market is an area of effective competition, comprising both product (or service) and geographic elements.”
Defendants likely will rely on United Airlines to argue that Optimum’s debt and negotiations surrounding that debt are not a relevant antitrust market. In United Airlines, the court wrote “[c]ompetition comes at the time loans are made… cooperation in an effort to collect as much as possible of the amounts due under competitively determined contracts is not the sort of activity with which the antitrust laws are concerned.”
Seemingly in response to this theory, Optimum’s complaint focuses on its lack of ability to pursue certain mechanisms under its debt agreements — such as accessing certain markets to raise or incur additional debt — as a result of the cooperation agreement effectively changing the terms agreed upon when the loan was originally made.
Optimum’s complaint asserts that at least two relevant product markets were impaired due to the defendants’ cooperation: “(1) the Leveraged-Finance Market, and (2) the Market for Outstanding Optimum Debt, which is a subset of the Leveraged-Finance Market,” with the relevant geographic market for both being the US. The complaint explains that these product markets “comprise U.S. borrowers (buyers) transacting with creditors (the sellers) investing in leveraged U.S. debt,” or stated more clearly, “Optimum is the buyer of credit, while creditors are the sellers.”
The complaint further explains that lev fin market includes transactions involving “the issuance of new debt, the post-issuance sale and purchase of debt on (including by borrowers), and transactions refinancing or exchanging already-issued debt,” and relates to leveraged loan and high yield bonds — but not investment grade bonds, nor equity finance, nor private loans which leveraged borrowers with low credit ratings do not reasonably have access to. Accordingly, the complaint argues these types of borrowers, among which Optimum is included, do not really have options outside the lev fin market.
The “Hypothetical Monopolist Test,” which the DOJ uses to help define relevant antitrust markets, asks “whether eliminating the competition among the group of products by combining them under the control of a hypothetical monopolist likely would lead to a worsening of terms for customers.” Here, the plaintiffs argue that in this market, a hypothetical monopolist could indeed “profitably impose a significant non-transitory price increase or quality reduction for the goods (leveraged loans and high-yield bonds) traded in that market” because of how inadequate the borrowers options are for raising capital outside the lev fin market, and the lack of available substitutes.
The plaintiffs similarly argue that ample evidence proves the cooperative has “market power” which it defines as “the ability to raise a product’s quality-adjusted price above competitive levels.” A few examples include (1) blocking the mechanism through which Optimum’s could capture discount by buying back its debt at prices below par, (2) remarks from PGIM to Optimum saying “we are the high-yield market,” (3) causing non co-op lenders to require a premium estimated around 200 to 300 basis points for extending a new loan which they would not be able to sell or syndicate, and (4) forcing the company to pay a premium to other similarly situated borrowers due to “thin investor base and liquidity constraints imposed by ‘co-op restrictions.’”
The complaint details the types of investor classes that the lev fin market is made up noting the leveraged loan market includes CLO managers, mutual funds, hedge funds, bank and insurance companies, and argues that the co-op represents 85% of the market. Additionally, according to the plaintiffs PJT, financial advisor to the co-op told Optimum that 99% of the company’s creditors are co-op members. Co-op members make up a similarly high percentage of the high yield bond market, according to the complaint — estimated at 92%. Ultimately the plaintiffs calculate that the co-op control 88% of the lev fin market.
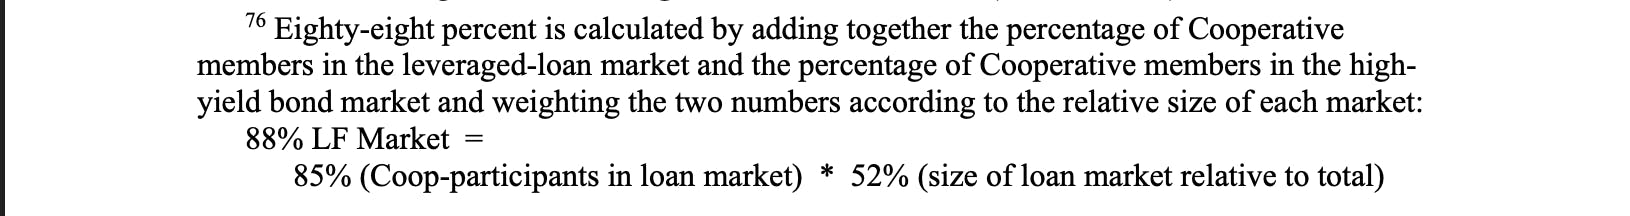
The complaint also point to a second relevant market: the “Market for Outstanding Optimum Debt” which is described a subset of the lev fin market. This market is where “Optimum engages in post-issuance transactions with creditors who hold Optimum’s debt to repurchase, refinance, exchange, or amend that debt.” The buyer and sellers as well as the goods are identical to the lev fin market, but is limited to one customer — Optimum. Accordingly, the plaintiffs argue the most realistic option is for Optimum to negotiate among existing creditors, and the existing creditors are exploiting that fact. The complaint asserts that the co-op has distorted prices by “effectively rewriting Optimum’s contracts and foreclosing it from accessing the discount that competition ordinarily produces” and distorting secondary prices.
Ultimately, defendants will still likely rely on United Airlines and the theory that they are simply cooperating ”to collect as much as possible of the amounts due under competitively determined contracts,” and that “this is not the sort of activity with which the antitrust laws are concerned.”
Antitrust injury — the difference between a bad break and a plausible claim (Sharon Steel)
The crux of the antitrust injury asserted by the plaintiffs is that the cooperation agreement prevented the company from engaging in contractually permitted transaction in the relevant markets. Four theories of harm are set out: (1) Optimum cannot transact or negotiate with co-op members for deleveraging transactions, (2) Optimum is blocked from competing with defendants to buy its own debt in the secondary market, (3) the price of Optimum’s debt is distorted and (4), Optimum is forced to pay elevated interest rates.
Defendants here are likely to rely on Sharon Steel where the court characterize the antitrust claims brought as “bordering[ing] on the frivolous.” In Sharon Steel, the company, like Optimum was not in fact insolvent, however, in that case the company did breach its indenture. The court in Sharon Steel opined that “joint activity by creditors facing a debtor is commonly in the interests of all parties,” since if they do not work together it could ultimately lead to a debtor going out of business and leaving its debts unsatisfied.
Optimum has and will continue to argue it was not in breach and any potential breach and related insolvency would only be due to the cooperation agreement. Defendants will likely argue that the company’s tactics under the debt documents that it cannot utilize here would have the result of leaving at least some of its debts unsatisfied. Similarly, while the company argues it has a right under the relevant debt agreements to negotiate with some groups over others and the cooperation agreement takes that right away, the court in Falstaff Brewing Corp, which allowed creditors to unite to negotiate pro rata language into its loans in exchange for covenant waivers might sympathize with the argument that these lenders are primarily trying to collect on credit they already extended, and therefore are not competing to supply more debt.
Pro-competitive or anti-competitive? choose your fighter (Falstaff)
The complaint asserts that the cooperation agreement has substantially harmed competition in the relevant markets since typically, members of the co-op would compete with each other by transacting with the company or other investors of the company’s debt. As a result of the cooperation agreement, plaintiffs argue, they are barred from this competition which impairs competition in the markets.
Plaintiffs categorize the co-op as a “per se illegal group boycott” explaining the agreement requires a “concerted refusal to deal.” Plaintiffs state that the agreement dictates that none of the creditors or their affiliates may transact with the company without the entire groups approval which has the result of banning the company from its relevant markets.
The complaint also alleges that the cooperative constitutes illegal price fixing given that the steerco has negotiated with Optimum on behalf of the entire co-op. As a result plaintiffs argue, they are limited to transacting at par or accepting new covenants that would functionally be the equivalent or raising the price of its debt.
Third, the complaints asserts that well-functioning markets rely on competition among creditors to set efficient terms and that LMEs “are an accepted market practice” that co-ops preclude a borrower from using. Perhaps predicting the creditors reliance on United Airlines, where as mentioned above the court said “[c]ompetition comes at the time loans are made… cooperation in an effort to collect as much as possible of the amounts due under competitively determined contracts is not the sort of activity with which the antitrust laws are concerned” the complaint argues that this cooperation agreement streps away the flexibility the borrower initially negotiated under the credit agreement and indentures — which would otherwise allow for a LME.
The plaintiffs further argue that although defendants have cast LMEs as a mechanism for creditor-on-creditor violence that needs prevention, creditors have the ability up front to negotiate language to prevent them, which creditors have done. They cannot instead obtain that benefit through “after-the-fact collusion,” contend the plaintiffs.
Fourth, the complaint alleges that the co-op suppresses output and depresses liquidity, pointing to the contrast in prices for members and non-members in the market, and historical data related to liquidity — noting a 66% drop in trading of Optimum bonds after the co-op was formed.
The complaint continues by alleging the anticompetitive effects go beyond Optimum, arguing creditors’ capital is locked up and cannot be deployed elsewhere in the lev fin market, and borrowers lack of faith in their contracts enforceability may prevent them from entering the market at all, which introduces inefficiencies in the relevant markets.
Plaintiffs argue that pro-competitive consideration does not justify the restraint on trade and unlike the previous case law relating to borrowers and creditors negotiations and cooperation — specifically Falstaff Brewing Corp — here there is no interest in facilitating mutual forbearance by creditors against a defaulting or insolvent creditor. And addressing the courts rationale in Sharon Steel that if creditors do not work together it could ultimately lead to a debtor going out of business and leaving its debts unsatisfied, plaintiffs argue the opposite is true here, the co-op accelerates the risk of bankruptcy.
Similarly, plaintiffs address United Airlines precedent where the court held “[c]ompetition comes at the time loans are made… cooperation in an effort to collect as much as possible of the amounts due under competitively determined contracts is not the sort of activity with which the antitrust laws are concerned.” Plaintiffs argue that the co-op does not “does not simply coordinate on a joint mechanism for enforcing Defendants’ existing repayment rights; it also bars future loans to Optimum and likewise restrains trading with respect to Optimum’s unmatured debt.” Still, defendants would likely argue that this falls under the ancillary restraints doctrine, which posits that agreements that are ancillary to otherwise lawful pro-competitive collaboration may be permissible.
Finally, plaintiffs argue that this is different than previous cases where courts allowed organization, since creditors are properly situated to compromise with borrowers — unlike indenture trustees — and here Optimum is not defaulting or insolvent, it is instead in full compliance with its contract.
Noerr-Pennington doctrine
The complaint seemingly does not allude to the Noerr Pennington doctrine which is “a judicially created doctrine that grants antitrust immunity to private parties petitioning the government,” even if those parties would otherwise be rivals and the coordination would otherwise be anticompetitive and has been extended by lower courts to permit parties with common legal rights to engage in joint efforts to enforce those rights. While we expect this will be addressed in the actual briefing, we expect plaintiffs to argue that it does not apply.
This complaint, drafted by the antitrust litigation specialist Kellogg Hansen (which appears to have no qualms about angering tons of lenders as they would have little to no business with them elsewhere), makes these various inferences and points all without mentioning the case law itself. What’s more, the particular co-op was across all of the different creditor classes and thus did not create the minority creditor group dynamic present in Selecta, the first lawsuit claiming harm that was caused by a co-op on antitrust grounds. We at 9fin expect that briefing will commence first in this case as well given the cross-border complications of Selecta. The balance of all these circumstances would suggest that this Optimum antitrust case is more than your average Hail Mary.