Ask anyone working in private credit about recent headlines, and you’ll likely get a chuckle, a grimace and the impression that some news coverage is more akin to ‘the boy who cried private credit crisis’ than reality.
And early fundraising data shows that investor appetite hasn’t fallen off a cliff in the wake of ‘punchy’ headlines.
As of Q1 26, managers raised $214.4bn LTM across direct lending and alternative credit strategies, compared to $268.8bn in the twelve months to Q1 25 and $163.4bn in the twelve months to Q1 24, according to With Intelligence by S&P Global.
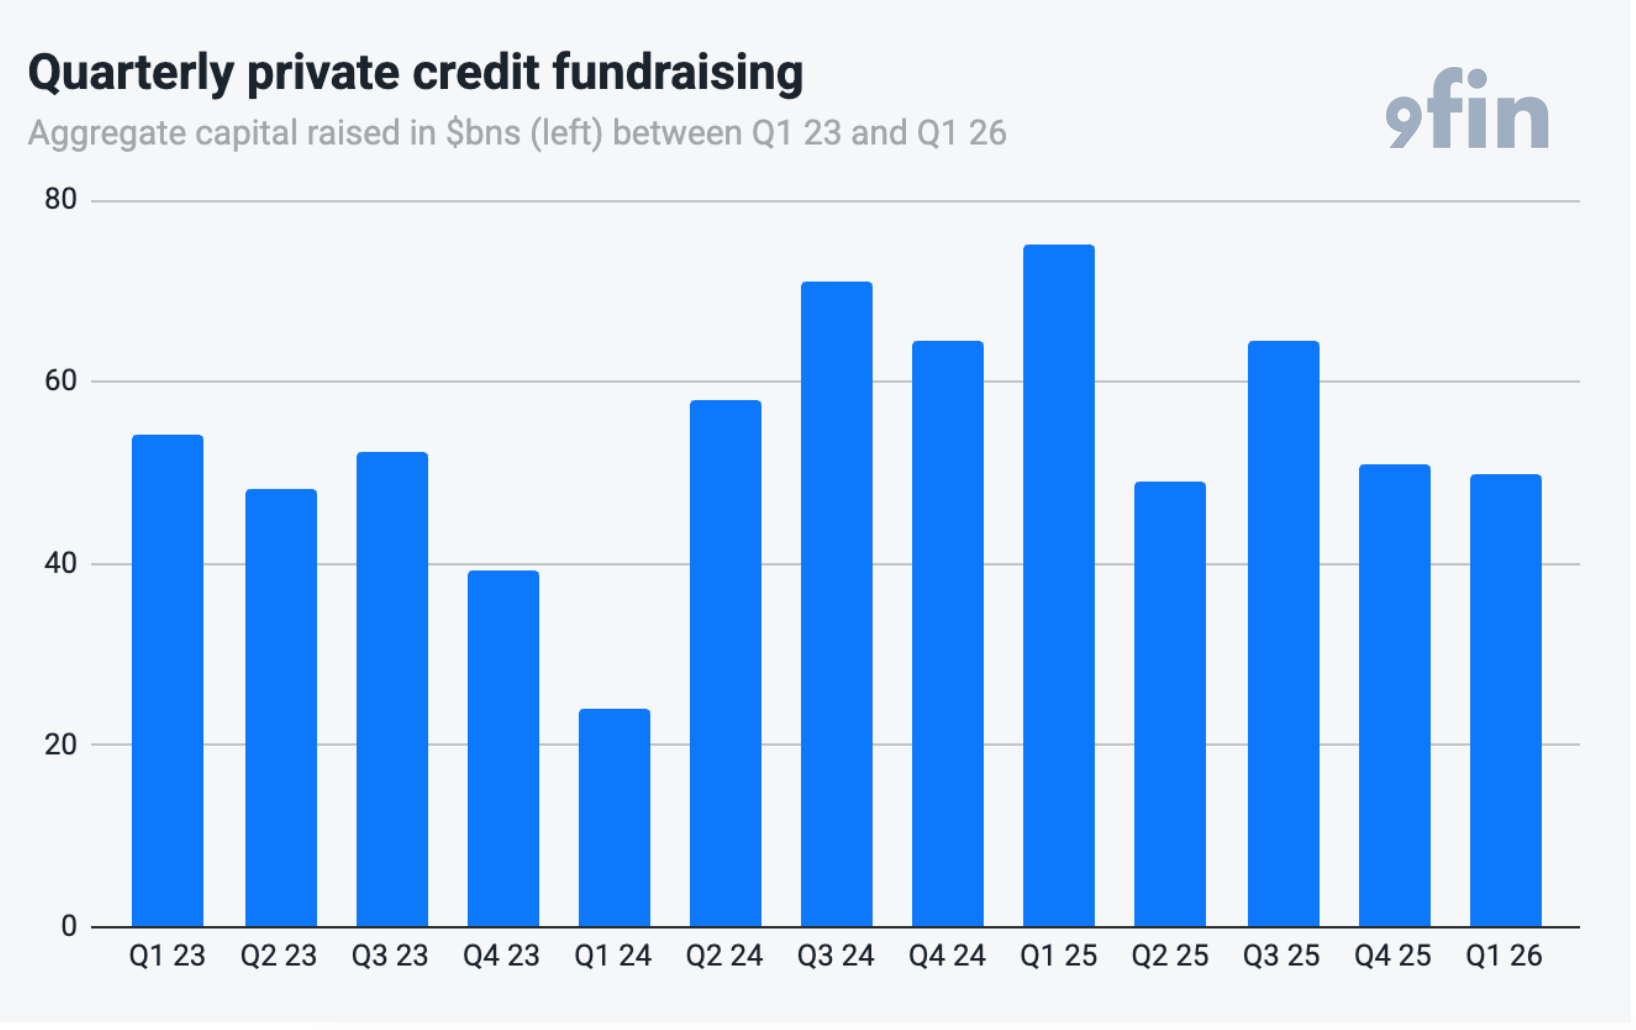
Source: With Intelligence by S&P Global
However if we look at different strategies within this fundraising, we see a different story.
Different strategies, different investor interest
Overall, early data suggests that fundraising remains stable.
Goldman Sachs, Arcmont and King Street have launched new direct lending funds seeking multi-billion figures from the likes of insurers, pensions, endowments and sovereign wealth funds — pools of ‘patient capital’ that have been investing in private markets since its early days.
Other names such as Ares, Blackstone, KKR and Monroe Capitalhave held final closes for institutionally-backed private credit strategies, raising over $28bn in...