The week began on Meta watch and ended with a surprise jumbo from Microsoft instead.
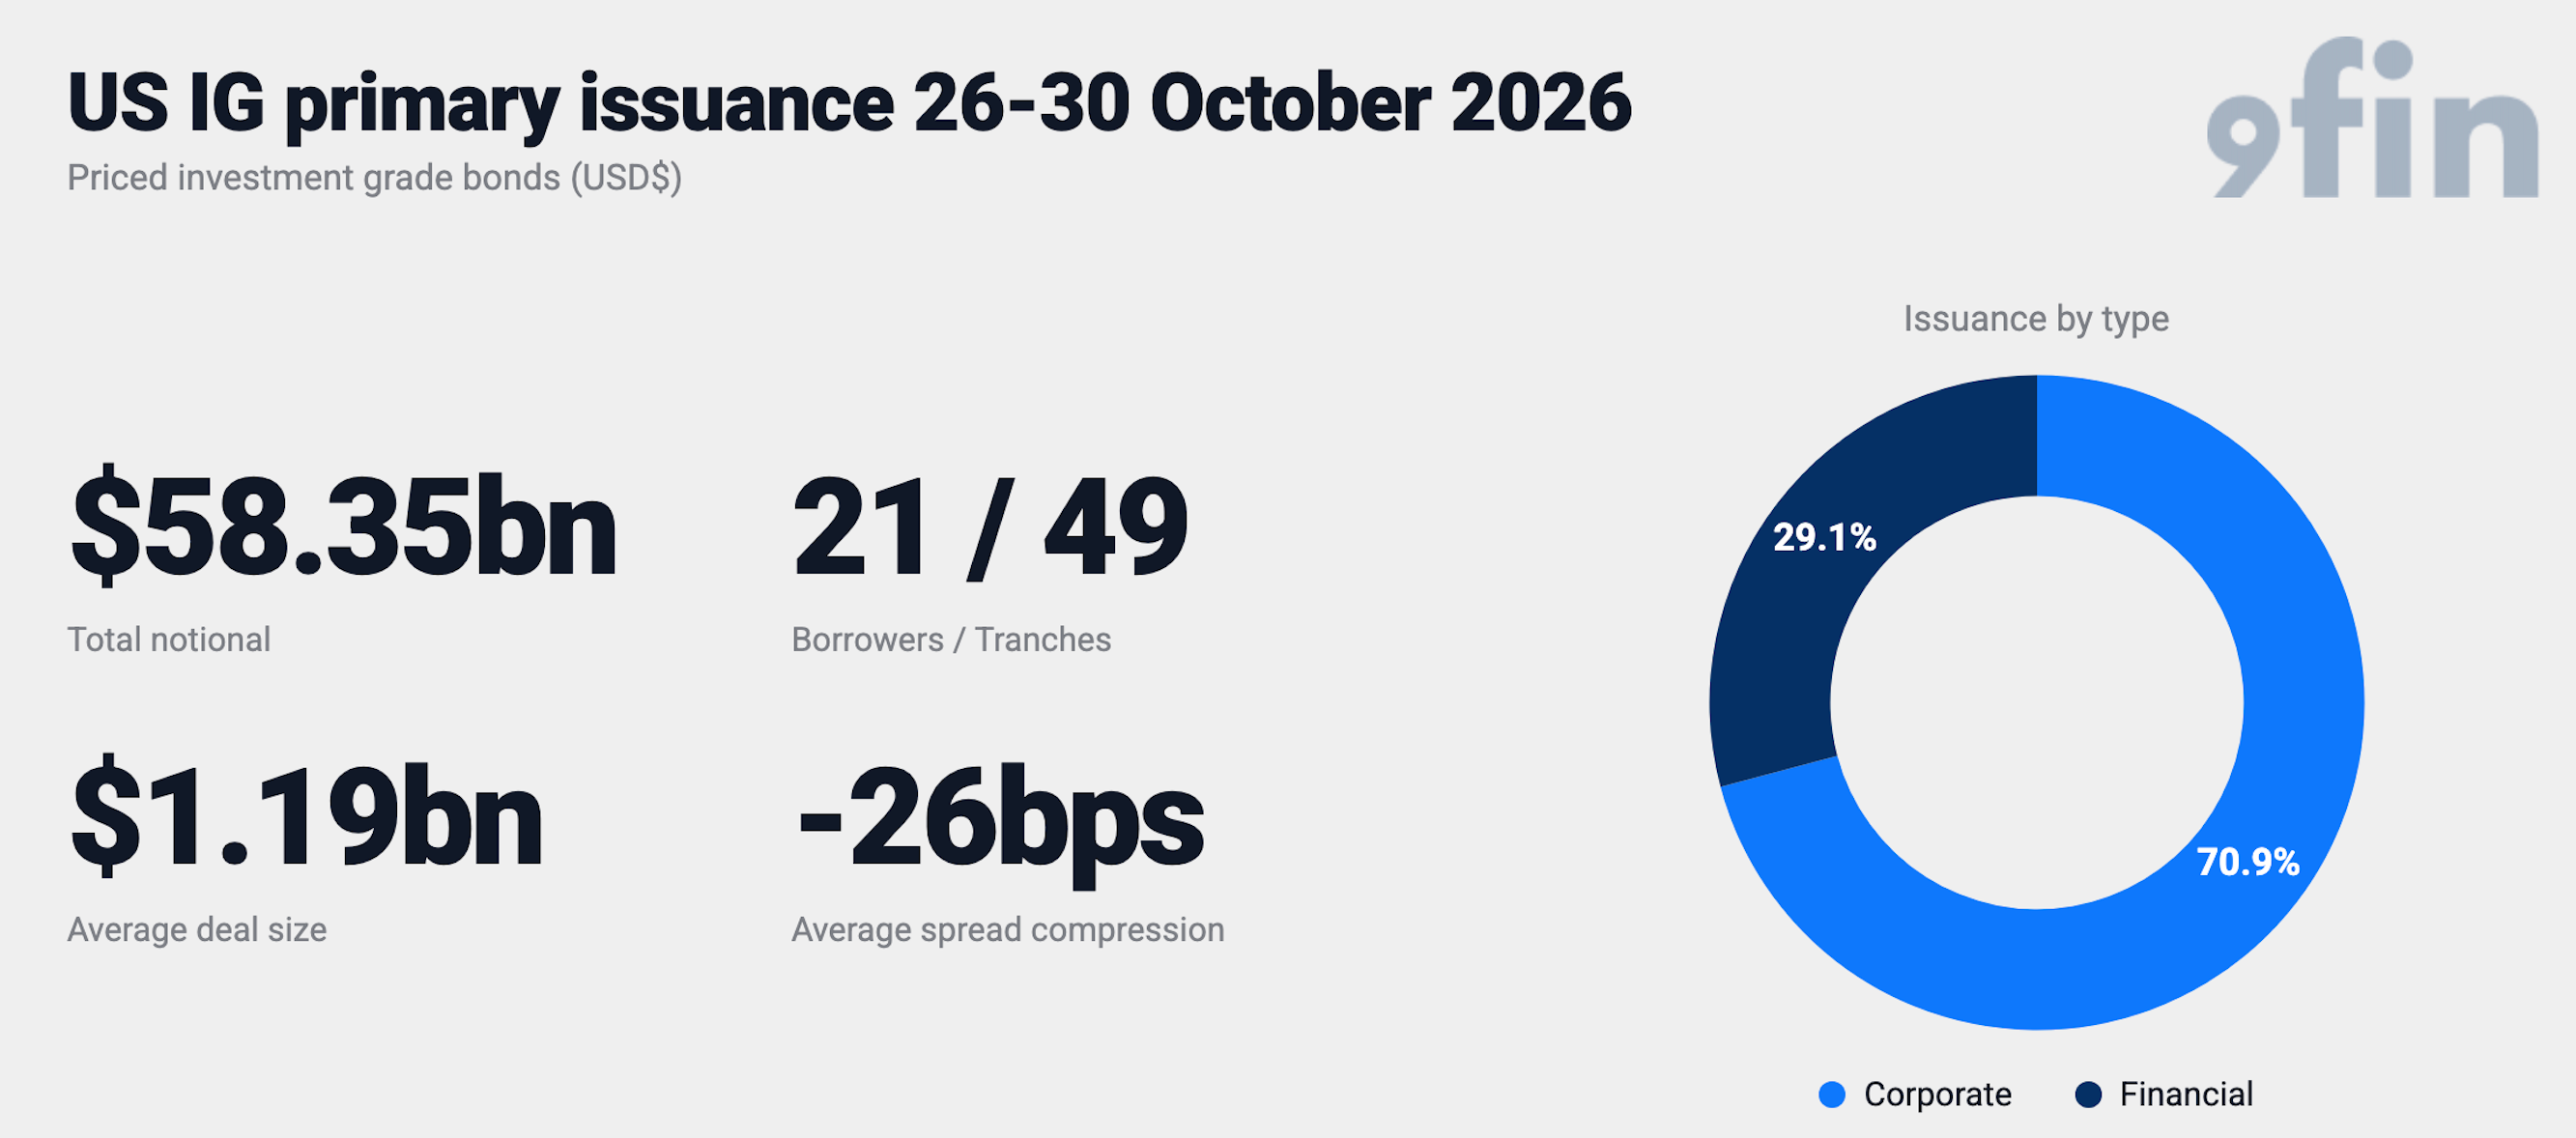
Microsoft tapped the debt market for the first time since 2017 with a $25bn offering that pushed US IG issuance to $58.35bn this week as investors weigh wider AI spreads and forecasts for a record November in supply.
The week brought October issuance to $119.95bn across 121 tranches from 57 borrowers, with nearly half the month’s volume arriving in its final week.
There could be plenty more to absorb. BofA Global Research forecasts $175bn of US IG issuance in November, which would make it the busiest November on record, compared to $138bn last year. Its forecast rests on post-earnings AI and acquisition financing, a backlog from October, and lower rates. It’s worth noting that the forecast came before Microsoft’s surprise deal this week.
AI and the Fed
Borrowers will still have timing decisions to make with mid-term elections taking place next week, but two themes are in focus. “We’re looking at what’s probably going to be an AI supply and Fed story for the rest of the year,” one buysider said.
The Federal Reserve, European Central Bank, and Bank of Japan all held rates unchanged...