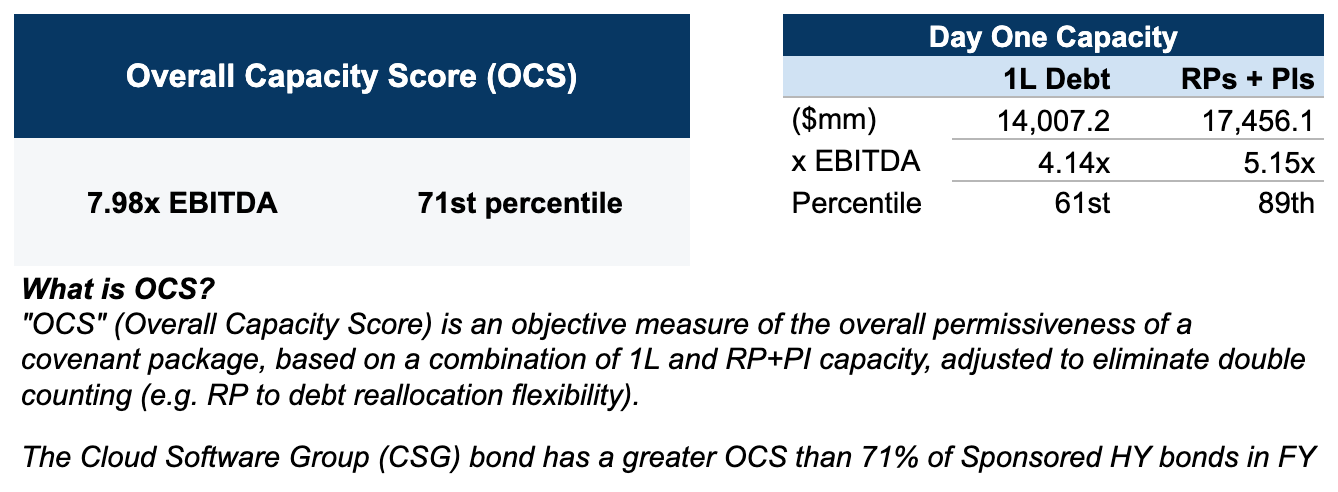
TLDR and OCS
The covenants are similar to the prior issuance and have most of the modern-day technologies found in recent top-tier sponsor deals.
Deal Overview
- Transaction Purpose: Together with cash on hand, to fund the repayment of up to $2,000m of 9.00% senior secured second lien notes due 2029
- Instrument:
- Sponsor: Vista Equity Partners, Evergreen Coast Capital (Elliott Investment Management)
- Preliminary Offering Memorandum on 9fin
- Covenant explorer on 9fin
- Credit QuickTake on 9fin
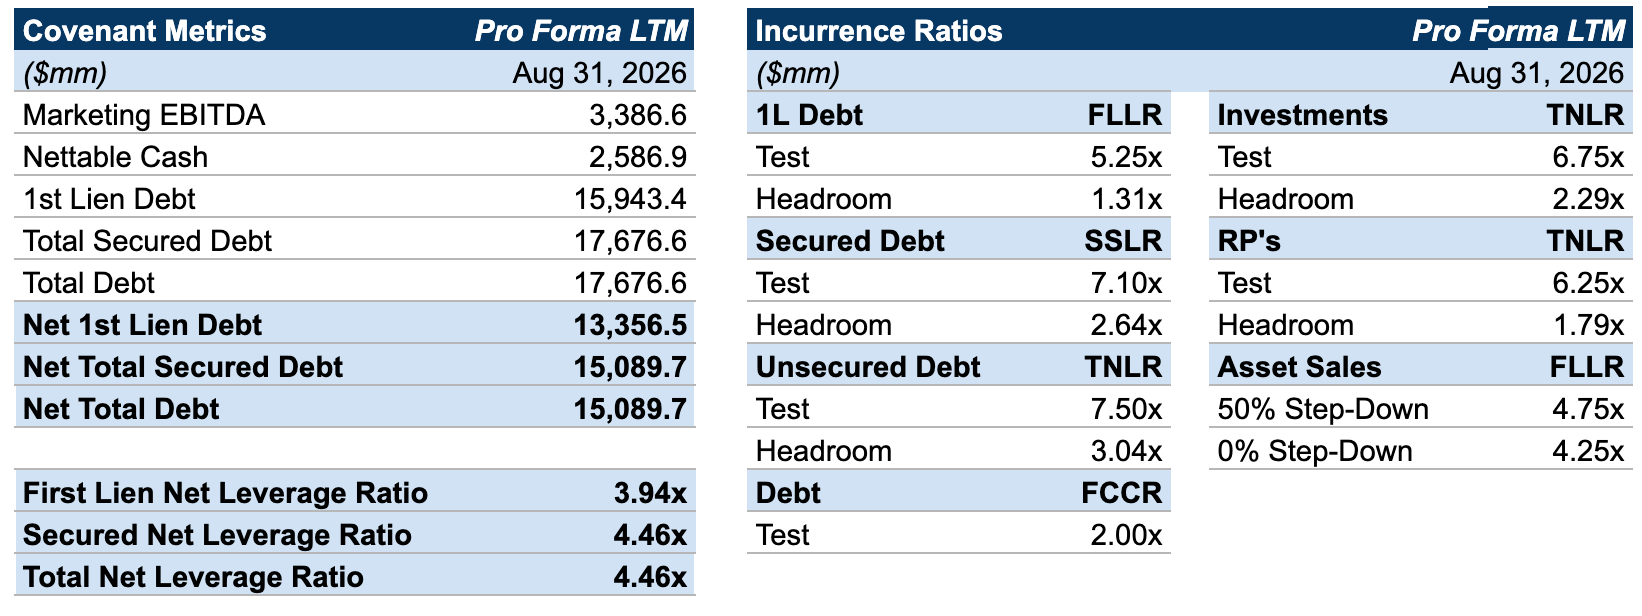
Key highlights
- General
- The notes will not benefit from the Midco parent guarantee that the credit facilities will benefit from
- Risk assessment
- Collateral dilution Risk: quantified under TLDR and OCS, above, which is slightly elevated due to the amount of incremental secured debt able to be incurred being in the 61st percentile
- Drop-down/dividend risk: quantified under TLDR and OCS, above, which is high due to the amount of RP + PI capacity being in the 89th percentile, largely driven by backdated RP builder basket capacity
- Structural subordination risk: The covenants permit the Issuer to transfer (or “invest”) all assets, including collateral, to or in non-guarantor restricted subsidiaries. Note also that there is no non-guarantor sub-limit for ratio debt or any other debt...